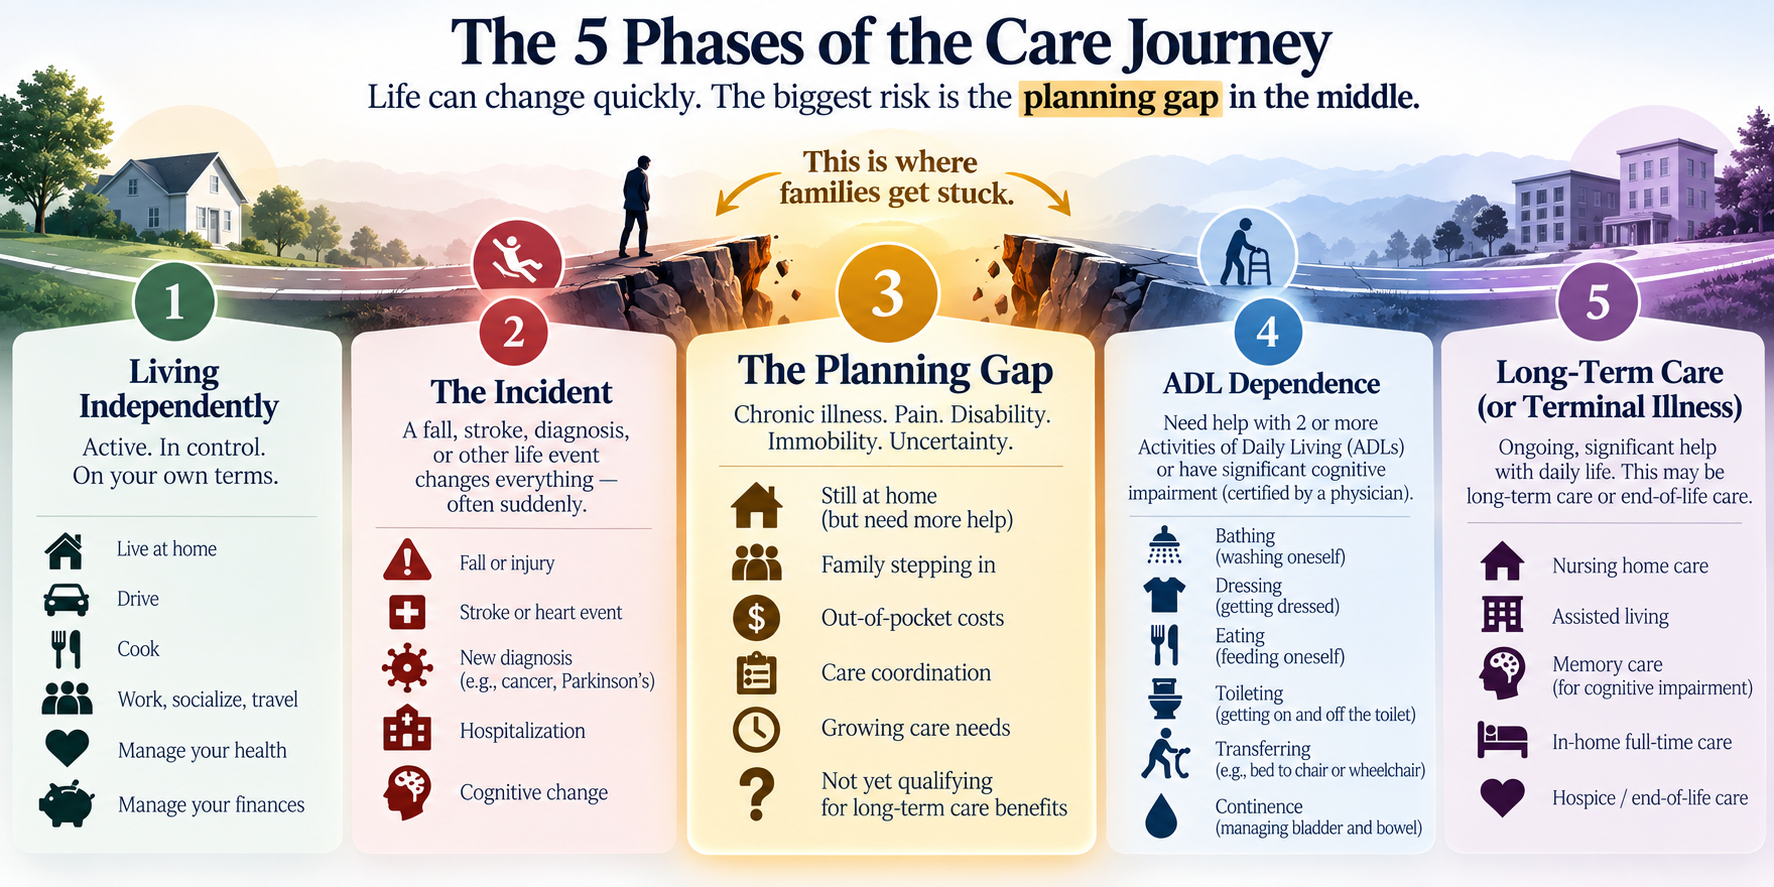
Are you ready for the 5 phases of the care journey?
When it comes to aging, there's something worse than needing long-term care. It's the gap between living independently on your own and long-term care. It's the gray area where Medicare, Medicaid, and long-term care benefits won't kick in.
Qualifying for long-term care is very specific. The insurance company underwriters take this seriously. You basically need a doctor and lawyer to figure it out.
2 out of 6 Activities of Daily Living or Significant Cognitive Impairment. If you have terminal illness, you can get some benefits. If you have chronic illness, that's a different story. You are diagnosed with cancer. You fall and spend months using a walker or wheelchair.
You can technically manage many of your daily activities, but your spouse or children are suddenly helping with appointments, errands, meals, and the house. You are still living at home, but your family is stepping in more often and the bills are starting to add up. Traditional financial planning tends to model the big long-term-care expense at the end.
Health insurance focuses on the medical treatment. Financial Care Planning focuses on the gap between them. I work with the financial side and care side to create boutique solutions for families facing this head on.
Call me when “they’re doing fine” starts to become “we probably need to figure this out.”